North American iGaming Expansion Outpaces Europe as SOFTSWISS Data Maps Growth Through 2028
Written by Morgan Peters · Oct 4, 2026
North American iGaming Expansion Outpaces Europe as SOFTSWISS Data Maps Growth Through 2028
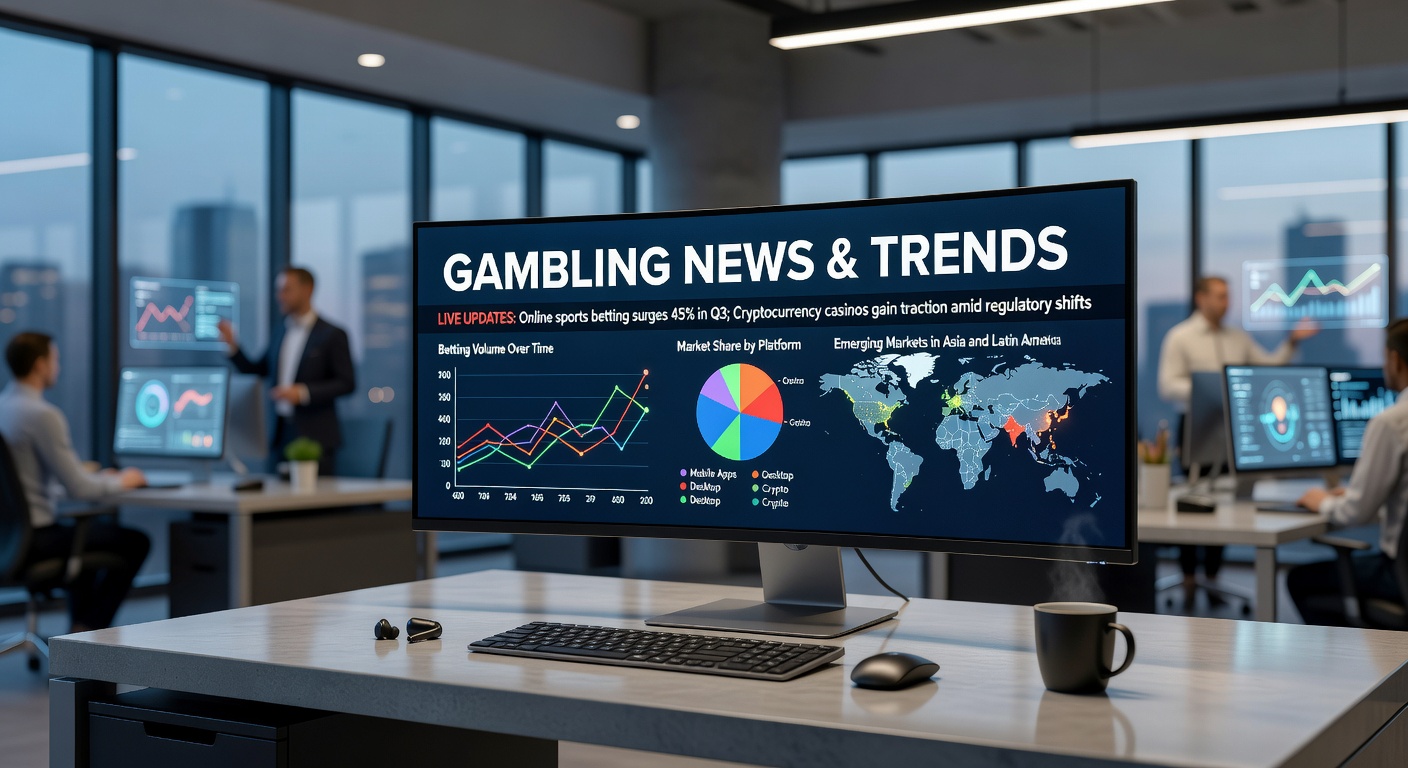
The SOFTSWISS iGaming Trends 2027 report lays out clear projections for the online gambling sector, and observers note that North America stands out as the fastest-growing major market through 2028. Data from the report places the region's compound annual growth rate at 15 percent, which exceeds Europe's projected 6 percent CAGR over the same period, and this divergence shapes how operators and regulators approach expansion plans.
Global online gambling gross gaming revenue receives a straightforward forecast in the same document, rising from 349 billion dollars in 2026 to 415.5 billion dollars in 2028, with mobile platforms driving much of the increase. The share of onshore GGR attributed to online channels climbs from 45 percent to 78 percent during those years, illustrating how device accessibility continues to reshape participation patterns across regions.
Market Fragmentation Shapes United States Trajectory
Within the United States the landscape remains divided by state-level regulations, and the report specifies that online casino operations hold legal status in only seven states. Growth concentrates heavily in Michigan, New Jersey, and Pennsylvania, which together accounted for nearly 90 percent of the 10.74 billion dollars in US online GGR recorded for 2025. Those three markets therefore serve as primary engines for the national total, while other states continue to evaluate or delay similar frameworks.
Analysts reviewing the SOFTSWISS figures point out that this concentration creates both opportunities and constraints for operators seeking broader national footprints. Because regulatory approval rests with individual legislatures, the pace of new market entries varies widely, yet the existing strongholds already demonstrate consistent revenue scaling that aligns with the overall 15 percent CAGR projection for North America.
Mobile Channels Fuel Broader Revenue Shifts
Mobile access underpins much of the projected global revenue climb, and the report ties this trend directly to rising onshore online shares. As smartphone penetration deepens and app-based platforms improve, operators see higher engagement rates that translate into sustained GGR growth through 2028. The transition from 45 percent to 78 percent online share of onshore totals reflects how players increasingly favor portable interfaces over traditional land-based venues.
Those who've examined similar past cycles note that mobile adoption often accelerates once initial regulatory clarity appears, and the current North American data supports that pattern. The 15 percent CAGR for the region therefore incorporates both expanded state approvals and deeper penetration within already active markets such as Michigan, New Jersey, and Pennsylvania.
Comparative Regional Performance Through 2028
Europe's slower 6 percent CAGR stands in contrast to North America's trajectory, and the SOFTSWISS report presents these figures side by side to highlight differing regulatory and consumer environments. While European markets maintain established frameworks in many jurisdictions, the pace of new player acquisition and revenue expansion appears steadier rather than explosive. North American growth, by comparison, benefits from a combination of newly legalized states and rapid mobile uptake within core markets.
The global totals remain anchored by these regional differences, with the overall rise from 349 billion dollars in 2026 to 415.5 billion dollars in 2028 depending on continued momentum in faster-growing areas. Data indicates that mobile's expanding role will continue to narrow the gap between onshore and online segments worldwide, regardless of regional regulatory pace.
State-Level Concentration and National Implications
Nearly 90 percent of 2025's 10.74 billion dollars in US online GGR originated from just three states, and the report underscores how this distribution influences near-term forecasts. Michigan, New Jersey, and Pennsylvania each maintain mature regulatory environments that support both casino and sports betting products, creating diversified revenue streams within the same platforms. Observers tracking legislative developments note that additional states considering legalization could further distribute these figures, yet current projections already embed the 15 percent CAGR based on existing momentum.
Because only seven states currently permit online casino activity, the remaining jurisdictions represent potential upside once policy decisions advance. The SOFTSWISS analysis therefore positions North America as the standout performer through 2028 while acknowledging that fragmentation still limits the speed at which the full national market can scale.
Conclusion
The SOFTSWISS iGaming Trends 2027 report supplies a focused set of projections that place North America ahead of Europe in online gambling growth rates through 2028, and the underlying numbers illustrate how mobile channels and concentrated state markets contribute to those outcomes. Global GGR moving from 349 billion dollars to 415.5 billion dollars during the period reflects these regional dynamics, while the US concentration in Michigan, New Jersey, and Pennsylvania continues to drive the majority of domestic results. Those monitoring regulatory developments will watch how additional state approvals interact with the established 15 percent CAGR path outlined in the data.